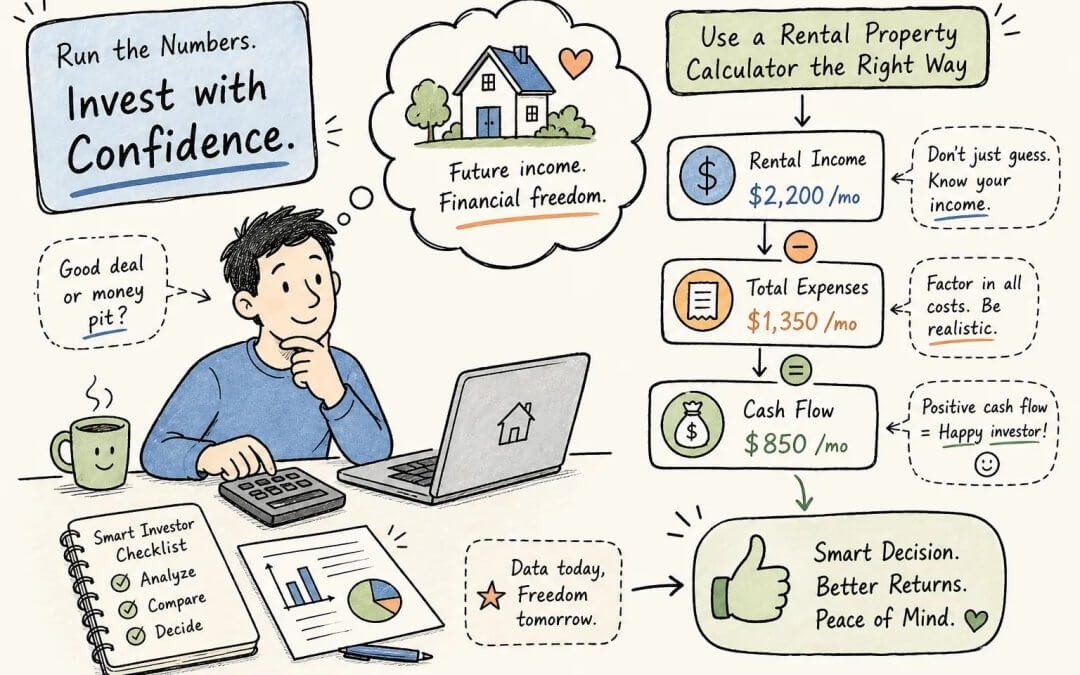
Before you fall in love with the photos, run the numbers through a rental property calculator. Many investors see a listing, imagine the rental income, and start mentally spending the cash flow before they’ve checked a single expense line. That emotional shortcut is exactly where portfolios lose money without the owner noticing, and it’s more common than most people admit.
A rental property calculator solves this by replacing gut feelings with math. It forces you to account for every income source and every expense before a property can make your shortlist. Experienced investors treat a thorough calculator run as a non-negotiable first step, not an optional sanity check, and the framework taught through Jason Hartman’s Empowered Investor Network is built around that exact discipline.
This article walks through the entire process: which inputs the calculator actually needs, what metrics it produces, how to benchmark those results against real market data, and how to compare multiple deals on equal terms. By the end, you’ll be able to run a complete analysis on any property and make a data-backed buy-or-pass decision with confidence.
What a rental property calculator actually tells you
A rental property calculator is more than a cash flow estimator. It is an underwriting engine that outputs several distinct metrics, and each one answers a different question about a deal. Understanding what each metric measures before you enter a single number prevents you from misreading the results later.
The four metrics every serious investor tracks
The four core outputs are net operating income (NOI), cap rate, cash-on-cash return, and IRR. NOI is what the property earns before any financing costs are applied. Cap rate measures property-level yield independent of how you finance the deal. Cash-on-cash return measures the yield on your actual out-of-pocket cash after debt service clears. IRR accounts for the full hold period, including appreciation and sale proceeds, and converts everything into a single annualized return figure.
When to use cap rate vs. cash-on-cash return
A cap rate calculator lets you compare properties regardless of financing structure, which makes it the right tool for evaluating whether a deal is priced well relative to its market. A cash-on-cash return calculator gives you your real-world annual yield after the mortgage payment, which makes it the right metric for evaluating how your actual dollars are performing. Two deals can have identical cap rates but completely different cash-on-cash returns if they carry different financing terms. Knowing which metric to lead with prevents you from comparing apples to oranges when evaluating competing opportunities.
Rental property calculator inputs: what you need before running the numbers
A rental property calculator is only as accurate as the numbers you feed it. Garbage in equals garbage out. The discipline is gathering every variable before you open the calculator, not filling in blanks as you go. Here is the full input stack in logical order.
Income inputs and how to estimate rent accurately
Gross rental income is your starting point. Use this section of your rental income calculator carefully, if the property generates secondary income from parking, storage, or pet rent, include that too. Then comes the input most investors underestimate: vacancy. A 5% vacancy assumption is standard for stabilized single-family rentals in healthy markets, while 7%-8% is more conservative and appropriate for newer markets or higher-turnover properties. Pull rent comps from local listing data or a local market specialist rather than relying on the calculator’s default figure, because that default is generic and your market almost certainly isn’t.
Operating expense inputs and realistic default ranges
The expense stack is where most investors leave money on the table by being optimistic. Property taxes typically run 1%-2% of purchase price depending on the state. Insurance is usually a fixed annual premium ranging from roughly $1,400 to $3,300 depending on market and property type, treat these as illustrative ranges, since your actual quotes will vary.
Maintenance and repairs should be modeled at 5%-10% of gross rent, or 1% of property value as a quick reserve rule. Property management fees run 8%-10% of collected rent for full-service management, though higher-rent coastal markets may sit closer to 6%-8% while smaller secondary markets often run 10%-12%. Include HOA dues if applicable. Many of these inputs are underestimated in a first-pass analysis, which artificially inflates projected cash flow and makes mediocre deals look attractive.
Financing inputs and their role in the calculation
Three financing inputs affect cash-on-cash return and IRR: down payment, interest rate, and amortization period. They do not touch cap rate, which is always calculated before debt service. For cash-on-cash and IRR analysis, the calculator needs your total cash invested, and that figure is not just the down payment. It includes the down payment plus closing costs plus any upfront repair costs. Using only the down payment as your invested capital base will overstate your cash-on-cash return and produce an IRR that doesn’t reflect what the deal actually costs you to execute.
How to read and benchmark your results
Running the numbers is only half the job. Knowing whether those numbers are strong, mediocre, or a hard pass requires benchmarks. Here is a worked example using real numbers, followed by market-type context for interpreting the results.
A worked example: putting the rental ROI calculator through its paces
Start with a $300,000 purchase price, a $60,000 down payment, and $10,000 in closing and initial repair costs, giving you $70,000 in total cash invested. Annual rent is $24,000, annual operating expenses are $9,000, and annual debt service is $8,400.
Here is how each metric flows from those inputs:
- NOI: $24,000 − $9,000 = $15,000
- Cap rate: $15,000 ÷ $300,000 = 5.0%
- Annual pre-tax cash flow: $15,000 − $8,400 = $6,600
- Cash-on-cash return: $6,600 ÷ $70,000 = approximately 9.4%
- IRR (5-year hold, $330,000 exit): Subtract selling costs and the remaining mortgage balance from the sale price to get net proceeds, add the final year’s $6,600 cash flow, and model the full cash flow stream from the initial −$70,000 outlay through to the sale. At these numbers, the IRR comes out to approximately 25% per year. In Excel, enter that stream into theXIRR function, which handles real calendar dates more accurately than a basic IRR formula.
What “good” looks like by U.S. market type
A 5.0% cap rate sits at the upper end of the typical range for gateway cities but would be considered mid-range or below average in many secondary Midwest markets. That context matters enormously. Primary and gateway markets typically trade at cap rates of 3.5%-5.5%, with cash-on-cash returns in the mid-single digits. Secondary markets, including Sun Belt metros like Charlotte, Memphis, and Indianapolis, generally see cap rates of 4.5%-7.5%, with cash-on-cash targets often in the 8%-12% range depending on leverage and strategy. Tertiary and rural markets price at 5.5%-9.0% or higher and require the highest cash yields to compensate for lower liquidity and higher tenant risk. The worked example above, a 5.0% cap rate and 9.4% cash-on-cash return, would represent a solid deal in a secondary Sun Belt market and a strong result in a gateway city.
How financing terms reshape every number
Two investors can buy the identical property and produce completely different calculator results based solely on their financing structure. The mechanics are worth understanding clearly so you don’t mistake a financing advantage for a property advantage.
Down payment and the leverage trade-off
There is an inverse relationship between down payment size and cash-on-cash return that catches many investors off guard. A larger down payment means more equity invested and less debt service, but because cash-on-cash return divides cash flow by total cash invested, putting more money in often lowers CoC if the property’s unlevered yield (its cap rate) isn’t strong enough to support it. Higher leverage can boost CoC and IRR when the property’s returns exceed the cost of borrowing, but it also amplifies risk on the downside. The right leverage level is a function of both the deal’s yield and your risk tolerance, not a universal rule.
Rate and amortization period effects on cash flow
Higher interest rates raise debt service directly, which compresses both cash flow and cash-on-cash return. A longer amortization period, say 30 years versus 20 years, lowers the required principal payment each month, improving near-term cash flow and CoC while leaving more unpaid principal on the books at sale. Run a quick sensitivity check by plugging in two different interest rate scenarios and observing how much the CoC shifts between them. That spread reveals exactly how vulnerable the deal is to rate changes, and it’s a fast check once your base inputs are in place.
Comparing multiple deals and knowing when to act
The real power of an investment property calculator is not analyzing one deal in isolation. It’s running the same consistent inputs across multiple properties and letting the numbers surface the winners. That discipline requires a bit of structure up front.
Setting up a side-by-side deal comparison
Keep all assumptions consistent across deals when comparing: same vacancy rate, same maintenance percentage, same management fee percentage. The only variables that should differ between deals are the property-specific inputs, purchase price, actual rent, and actual taxes. When you control for methodology, you’re comparing properties fairly rather than stacking optimistic underwriting on one deal against conservative underwriting on another. Look for the deal with the highest cash-on-cash return at your target leverage level, the strongest cap rate relative to its market type, and the IRR scenario that best aligns with your intended hold period.
Running the numbers on vetted, pre-screened properties
Knowing the framework is one thing. Having accurate local inputs, actual rent estimates, real tax rates, real management costs, is another challenge entirely, especially when you’re investing out of state. The Empowered Investor Network offers tools and consultations designed to help investors plug real, market-specific data into their analysis on properties that have been sourced and reviewed across multiple U.S. markets. Instead of guessing at vacancy rates or calling three property managers to estimate fees, investors can work with data that reflects what the deal actually looks like on the ground. For anyone who has learned the underwriting framework but isn’t confident in their market assumptions, that kind of guided support turns the rental property calculator from a theoretical exercise into a real acquisition decision.
Put the calculator to work on a real deal
A rental property calculator is not a magic number generator. It is a discipline. The quality of your output depends entirely on the accuracy of your inputs and your ability to benchmark results against the right market context. That combination, accurate inputs plus proper benchmarking, is what separates investors who consistently make smart acquisitions from those who rely on optimism and regret it later.
The process comes down to four steps: gather every income and expense input before you open the calculator; keep your cap rate analysis separate from your cash-on-cash analysis because they answer different questions; stress-test your financing assumptions across at least two interest rate scenarios; and always compare multiple deals using identical methodology. The investors who get this right aren’t smarter. They’re more systematic.
Your next step is straightforward: pull a real property, enter real numbers, and let the calculator tell you whether it’s a deal or a pass. If you want to start with properties that already have verified local data behind them, reach out to the Empowered Investor Network team for a consultation and see what the numbers look like on screened properties across active U.S. markets.