Many new investors confuse gross rent with profit. They look at a $2,000/month rental, subtract the mortgage, and call it cash flow. That math ignores taxes, insurance, management fees, maintenance, vacancies, and a dozen other costs that quietly consume what looked like a solid return. A proper cash flow analysis for real estate is not complicated, it’s a sequence of four steps, and every number in that sequence has a name and a formula. Get them right, and you know what you’re buying. Get them wrong, and you find out after closing, once the property is yours.
This article walks through the complete framework for rental property cash flow analysis: from gross rent down to actual cash flow, through NOI, cap rate, and cash-on-cash return, with the same $200,000 property used as the running example throughout. The math works the same whether you own one unit or forty.
Real Estate Cash Flow Analysis: How Rental Property Cash Flow Works
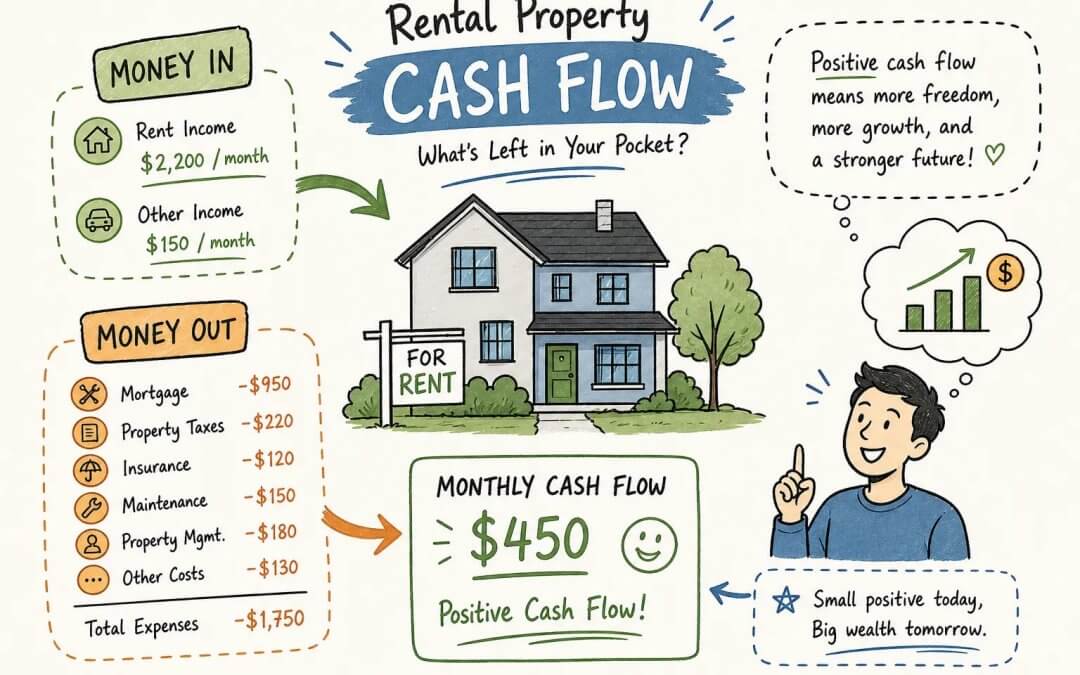
The foundation is a simple sequence. Start with what the property earns. Subtract what it costs to operate. Subtract what you owe the bank. What’s left is your cash flow. Each step in that sequence has a specific name, and the distinctions matter because different metrics answer different questions.
Cash Flow Analysis for Real Estate: The Four-Step Formula
- Gross Rental Income, the full scheduled rent, assuming the unit is occupied and paying.
- Effective Gross Income (EGI), gross rent minus your vacancy allowance, which reflects realistic occupancy.
- Net Operating Income (NOI), EGI minus all operating expenses.
- Cash Flow, NOI minus your mortgage payment (debt service), which is what actually lands in your account.
The most important distinction in that sequence is between NOI and cash flow. NOI is before financing. It measures the property’s income-generating ability regardless of how it’s funded. Cash flow is after financing. Mortgage principal is not an operating expense; it is a financing cost, and it belongs below the NOI line.
A real monthly and annual example
Take a $200,000 single-family rental with $2,000/month in gross rent. Apply a 5% vacancy allowance ($100), which leaves an EGI of $1,900. Operating expenses break down as follows: property taxes ($200), insurance ($100), property management ($160, or 8%), repairs and maintenance ($150), and HOA ($50), totaling $660/month. Subtract those from EGI: $1,900 minus $660 equals an NOI of $1,240/month. With a $900/month mortgage payment, monthly cash flow is $340. Multiply by 12: the property generates $4,080/year in cash flow, with an annual NOI of $14,880.
NOI and Cap Rate: The Two Metrics Every Property Gets Measured By
NOI and cap rate are the benchmarks used to evaluate whether a property’s income justifies its price. Both metrics exclude financing, which makes them useful for comparing properties across different loan structures, markets, and ownership situations. They answer the same underlying question: is this property priced right relative to what it produces?
How to calculate net operating income step by step
Start with Effective Gross Income, which is gross rent minus vacancy. From there, subtract all operating expenses: property taxes, insurance, property management fees, maintenance, HOA, and any owner-paid utilities. The result is NOI. What does not go into this calculation: mortgage payments, depreciation, capital expenditures (CapEx), and income taxes. Those are either financing costs or owner-level accounting items that have no place inside the NOI figure.
Using the example property: EGI of $22,800 annually minus $7,920 in annual operating expenses equals an NOI of $14,880. That number is clean, financing-agnostic, and directly comparable to any other property on the market.
Using cap rate to evaluate a property’s price
Cap Rate equals NOI divided by purchase price. For this property: $14,880 divided by $200,000 equals a 7.4% cap rate. That tells you the unlevered yield you’d earn if you bought the property with all cash and no mortgage. Cap rate is most useful for comparing properties side by side or sanity-checking whether a seller’s asking price is reasonable given market conditions. Experienced investors in affordable U.S. markets in 2026 treat cap rates in the 6% to 8% range as a solid baseline; 8% and above is strong cash-flow territory.
Cap rate has one meaningful limitation worth understanding: it does not tell you your actual return when you’re using a mortgage. For that, you need a different metric entirely.
Cash-on-Cash Return: The Metric That Tells You If Your Money Is Working
Cash-on-cash return is where financing enters the equation. Unlike cap rate, it measures annual pre-tax cash flow against the actual cash you put into the deal. It answers the question your bank account actually cares about: for every dollar I invested, how much cash am I getting back each year?
How to calculate cash-on-cash return
The formula is straightforward: Cash-on-Cash Return equals Annual Before-Tax Cash Flow divided by Total Cash Invested. Total cash invested includes your down payment, closing costs, and any upfront repair budget or improvements. On this $200,000 property, assume 20% down ($40,000) plus $15,000 in closing costs and an upfront repair budget, for $55,000 total cash in. Annual cash flow of $4,080 divided by $55,000 equals roughly 7.4% cash-on-cash return.
What a good cash-on-cash return looks like in 2026
Many experienced investors target 8% or higher, though acceptable thresholds vary by market and investment objective. In high-appreciation Sun Belt markets, a 6% to 7% return may still make sense if the growth trajectory justifies accepting a lower current yield. In flat Midwest markets where appreciation is modest, that same 6% return deserves harder scrutiny. Across major U.S. investment markets in 2026: 6% to 8% is good, 8% to 12% is strong, and 12%+ typically signals more risk, a value-add component, or unusually favorable financing.
Expense and Vacancy Benchmarks: Don’t Underestimate These Inputs
Bad underwriting almost always comes down to understated expenses, not overestimated rent. Sellers’ pro formas routinely show low vacancy, minimal maintenance, and no CapEx reserves. Those omissions inflate projected cash flow and set up buyers for unpleasant surprises. Using realistic benchmarks is not pessimism; it’s basic discipline.
Operating expense ratios by property type
Single-family rentals typically run 35% to 45% of effective gross income in operating expenses, with newer homes in efficient, low-tax markets landing on the lower end. Small multifamily properties (2 to 4 units) run 40% to 50% because shared systems and higher turnover tend to push costs up. The 50% rule, which assumes half your gross rent covers expenses before debt service, is a reasonable screening shortcut. It tends to overstate expenses on newer, well-located single-family rentals and understate them on older properties in high-tax markets. Use it to screen deals quickly, then replace it with line-item analysis on anything worth pursuing seriously.
Vacancy rates and CapEx reserves by market type
For stable, high-demand markets, budget 5% vacancy. For softer or more transient markets, use 8% to 10%. CapEx reserves should be 10% to 15% of annual gross rent for most properties, with older assets requiring the higher end of that range. Skipping CapEx reserves is one of the most common mistakes in beginner pro formas. A roof, an HVAC system, or a water heater will eventually need replacing, and that cost does not disappear because you left it off the spreadsheet. Build the reserve in from day one, and your cash flow projection reflects what the property will actually deliver over time.
How Your Loan Terms Reshape Every Number in the Model
Two investors can buy the exact same property and walk away with completely different cash flows. The variable that explains the gap is almost always financing. Interest rate, loan-to-value ratio, and amortization period all interact to determine debt service, and debt service is subtracted directly from NOI to produce cash flow.
Interest rate, LTV, and amortization: what moves the needle most
Higher interest rates increase debt service directly, shrinking cash flow dollar for dollar. Longer amortization periods reduce the annual principal repayment component, lowering monthly payments and improving cash flow. Higher LTV means more debt, which raises annual payments but lowers the cash required at closing. Consider the same $200,000 property financed at 80% LTV (a $160,000 loan) at 6.5% versus 7.5% on a 30-year amortization schedule: the difference in monthly payment is roughly $100 to $110, which compounds to over $1,200 annually in cash flow impact. Stress-test your model across two or three rate and LTV combinations before committing to a deal. The range of outcomes matters as much as the base case.
DSCR: the lender’s metric you need to understand
Debt Service Coverage Ratio equals NOI divided by annual debt service. Most U.S. lenders in 2026 require a DSCR of 1.2 or above for investment property loans, meaning the property must generate at least 20% more income than needed to cover the loan payment. Calculate DSCR before you talk to a lender, not after. DSCR-based loan products have become a mainstream financing tool in 2026; they qualify borrowers based on property income rather than personal W-2 income, which makes them especially relevant for investors with complex tax returns or multiple income streams. Standard requirements typically include a 1.2x DSCR, 20% to 25% down, a 620 to 680 minimum credit score, and 3 to 6 months of reserves.
Discounted cash flow analysis: the longer view
For investors evaluating a hold period of five years or more, discounted cash flow (DCF) analysis adds another layer of precision to real estate underwriting. DCF projects your expected cash flows year by year, accounting for rent growth, expense escalation, and an estimated sale price, then discounts those future dollars back to present value using a target rate of return. The result is an internal rate of return (IRR) and net present value (NPV) that let you compare a real estate investment against other asset classes on an apples-to-apples basis. It’s a more advanced tool, but the inputs are the same ones you’ve already been building: NOI, debt service, and realistic operating assumptions.
How the Empowered Investor Network Vets Deals Before You Ever See Them
Running a rigorous rental property cash flow analysis requires accurate inputs: local rent comparables, realistic property tax figures, market-specific management fees, and vacancy rates that reflect actual conditions in that submarket, not national averages. Most investors buying outside their home state don’t have access to those inputs. Some guess. Others use round numbers or take the seller’s pro forma at face value. Each approach introduces risk that doesn’t surface until after closing.
AI tools and investment counselors that run the analysis for you
At The Empowered Investor Network, every property goes through a structured underwriting process before it reaches a client. That process combines AI-powered cash flow tools with dedicated investment counselors who apply realistic NOI assumptions, market-specific operating expense ratios, and stress-tested debt service scenarios. A property has to clear a minimum profitability threshold before it gets recommended, and that standard is applied consistently across markets and deal types. If you want to see what that process looks like on a specific property, reach out to schedule a free consultation.
Why this matters when you’re investing outside your home market
Small input errors compound fast. Getting the property tax rate wrong by $50/month, using an 8% management fee when the local market runs 10%, and underestimating vacancy by two percentage points: none of those mistakes looks catastrophic on its own. Together, they can flip a deal that modeled at 8% cash-on-cash return into one that actually delivers 4%. Out-of-state investors often don’t know what they don’t know about local market conditions. The investment counselors at the Empowered Investor Network work directly with local market specialists in each target city, so the underwriting numbers reflect ground-level reality rather than generic benchmarks. For investors building a multi-state portfolio without the time to become a spreadsheet expert in a dozen markets, that infrastructure is how smart acquisitions get made.
Run the Numbers Before You Make an Offer
The framework is not complicated. Cash flow equals income minus operating expenses minus debt service. NOI and cap rate evaluate the property independent of financing. Cash-on-cash return measures the actual yield on your invested equity. Expense and vacancy inputs matter more than most investors realize, DSCR tells you whether the lender will agree with your math before you’ve spent money on inspections and appraisals, and a discounted cash flow model extends that analysis across your full hold period.
None of this requires a finance degree. It requires discipline and honest inputs. Do a complete cash flow analysis for real estate before you make an offer, not after. The investors who get burned are almost never the ones who ran thorough numbers and got them slightly wrong. They’re the ones who skipped the analysis entirely, or trusted a pro forma they didn’t build themselves. That single habit, running the numbers first, is what separates investors who actually build wealth through real estate from those who learn expensive lessons.
Frequently Asked Questions
What is cash flow analysis in real estate?
Real estate cash flow analysis is the process of calculating how much income a rental property generates after all operating expenses and debt service are paid. It moves from gross rent to effective gross income, then to NOI, and finally to after-financing cash flow, the number that reflects what actually hits your bank account.
What is a good cash-on-cash return for a rental property?
In most U.S. markets in 2026, a cash-on-cash return of 6% to 8% is considered solid, 8% to 12% is strong, and anything above 12% typically involves elevated risk, a value-add component, or unusually favorable financing terms. Targets also shift by market: high-appreciation markets may justify lower current yields.
How do I calculate net operating income (NOI)?
NOI equals effective gross income (gross rent minus vacancy) minus all operating expenses, including property taxes, insurance, management fees, maintenance, and HOA dues. Mortgage payments, depreciation, and CapEx are excluded from the NOI calculation.
What DSCR do lenders require for investment properties?
Most U.S. lenders in 2026 require a minimum DSCR of 1.2, meaning the property’s NOI must be at least 20% higher than the annual debt service. DSCR loan products qualify borrowers on property income rather than personal income, making them a widely used tool for real estate investors.
What is a rental cash flow template?
A rental cash flow template is a spreadsheet or structured worksheet that walks you through each line item in the cash flow sequence, gross rent, vacancy, operating expenses by category, NOI, debt service, and final cash flow, so you can run consistent, comparable analysis across multiple properties. The Empowered Investor Network provides investors with underwriting tools and counselor support to build accurate projections on target properties.